Global Markets End Week on Strong Note as US Stocks Near Records, Oil and Yields Keep Investors Alert
Global equity markets closed the week with a broadly positive tone, led by strong gains on Wall Street, while investors continued to closely monitor elevated crude oil prices, bond yields, inflation expectations and the upcoming corporate earnings season. The latest global market data shows that sentiment remains constructive, but the investment environment is becoming increasingly selective.
According to market data tracked by Groww, major global indices including the Dow Jones, S&P 500, Nasdaq, Hang Seng, DAX, FTSE 100 and KOSPI continued to reflect significant regional differences in performance. Groww also cautions that its global-index figures are CFD prices and may differ from prices directly reported by exchanges.
Wall Street Leads Global Gains
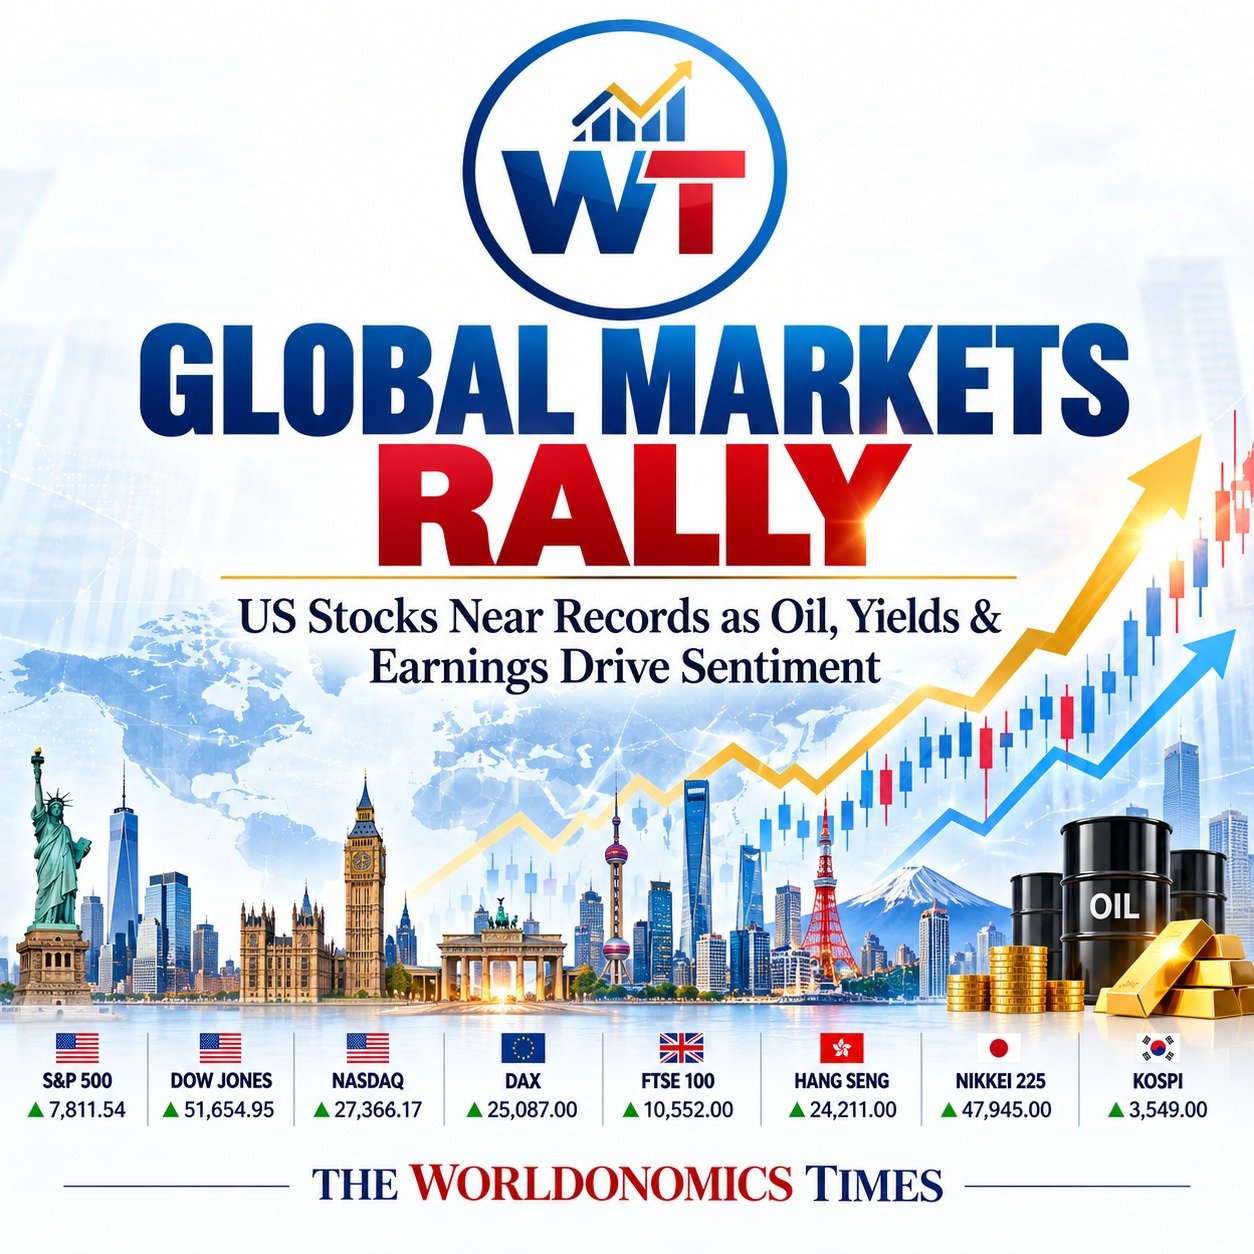
The United States remained the strongest major market during Friday’s session. The S&P 500 gained 0.6% to 7,811.54, while the Dow Jones Industrial Average rose 0.8% to 51,654.95. The technology-heavy Nasdaq Composite advanced 0.6% to 27,366.17.
The weekly performance was also encouraging. The S&P 500 gained approximately 1.2% for the week, the Dow added 0.9%, and the Nasdaq advanced 0.6%. On a year-to-date basis, the Nasdaq remained the standout performer, gaining around 17.7%, compared with 14.1% for the S&P 500 and 7.5% for the Dow.
The gains indicate that investors continue to favour large, profitable technology and growth companies despite higher financing costs. However, market participation remains relatively narrow, increasing the importance of upcoming earnings results.
Europe Shows Signs of Recovery
European equities also finished the week positively. The pan-European STOXX 600 gained about 1% on Friday, recovering from losses earlier in the week. Germany’s DAX and Britain’s FTSE 100 were among the important benchmarks being watched by international investors. Groww’s latest data showed the DAX around 25,087, while the FTSE 100 was around 10,552.
European markets, however, remain sensitive to inflation, fiscal concerns and government borrowing costs. France has attracted particular attention because of concerns surrounding its public finances and political outlook.
Asia Remains Mixed
Asian markets delivered a mixed picture. The Hang Seng was around 24,211, while South Korea’s KOSPI was under pressure, falling 2.62% in the latest Groww data. Japan’s Nikkei remained comparatively resilient.
For Asian investors, the direction of US technology stocks, semiconductor demand, currency movements and China’s economic outlook remain important market drivers.
Oil and Bond Yields Remain Key Risks
One of the biggest challenges for global investors is the combination of elevated energy prices and high bond yields. Brent crude remained around $104 per barrel, while the US 10-year Treasury yield stood near 5.26%.
Higher oil prices can increase inflationary pressure, while elevated bond yields raise borrowing costs for governments and companies. Together, these factors can limit the valuation multiples investors are willing to pay for growth stocks.
Earnings Season in Focus
The next major catalyst for markets will be the US third-quarter earnings season, particularly results from major banks and large technology companies. Investors will be looking beyond headline profits to assess whether corporate earnings can justify current valuations in an environment of expensive capital and elevated geopolitical risks.
Gold also remained strong, rising approximately 1.5% to around $4,193 per ounce, reflecting continued demand for defensive assets.
The Worldonomics Times View
The global market outlook entering the new week remains cautiously optimistic. Strong US equity performance provides support to global sentiment, but investors face several potential sources of volatility—including oil prices, inflation, interest-rate expectations, geopolitical developments and corporate earnings.
For Indian investors, global market movements will remain important for the opening direction of domestic equities, currency movements, foreign institutional flows and sector rotation. The key message from global markets is clear: momentum remains positive, but risk management and earnings quality are becoming increasingly important.