HDFC Bank declined 2.3%, while Axis Bank fell 4.2%, contributing significantly to the weakness in financial stocks. Analysts indicated that the selling appeared to reflect a combination of profit-taking following the previous week’s rally and concerns about margins rather than a complete deterioration in the banking sector’s fundamentals.
The broader market also witnessed selling pressure. Small-cap and mid-cap indices declined around 1%, highlighting the cautious mood among investors.
However, public-sector banks moved in the opposite direction. The PSU Bank index gained about 2.5%, supported by strong performances from Punjab National Bank and Union Bank of India. Punjab National Bank rose 4.8%, while Union Bank gained 5.3% following encouraging quarterly developments.
The latest Groww market data also highlights the wide range of Indian benchmarks available to investors, including Nifty 50, Bank Nifty, Nifty IT, Nifty Pharma, Nifty Auto, Nifty Midcap and Nifty Smallcap indices.
Global Markets Remain Mixed
International markets presented a mixed picture as investors assessed the technology-sector sell-off and awaited another important week of corporate earnings.
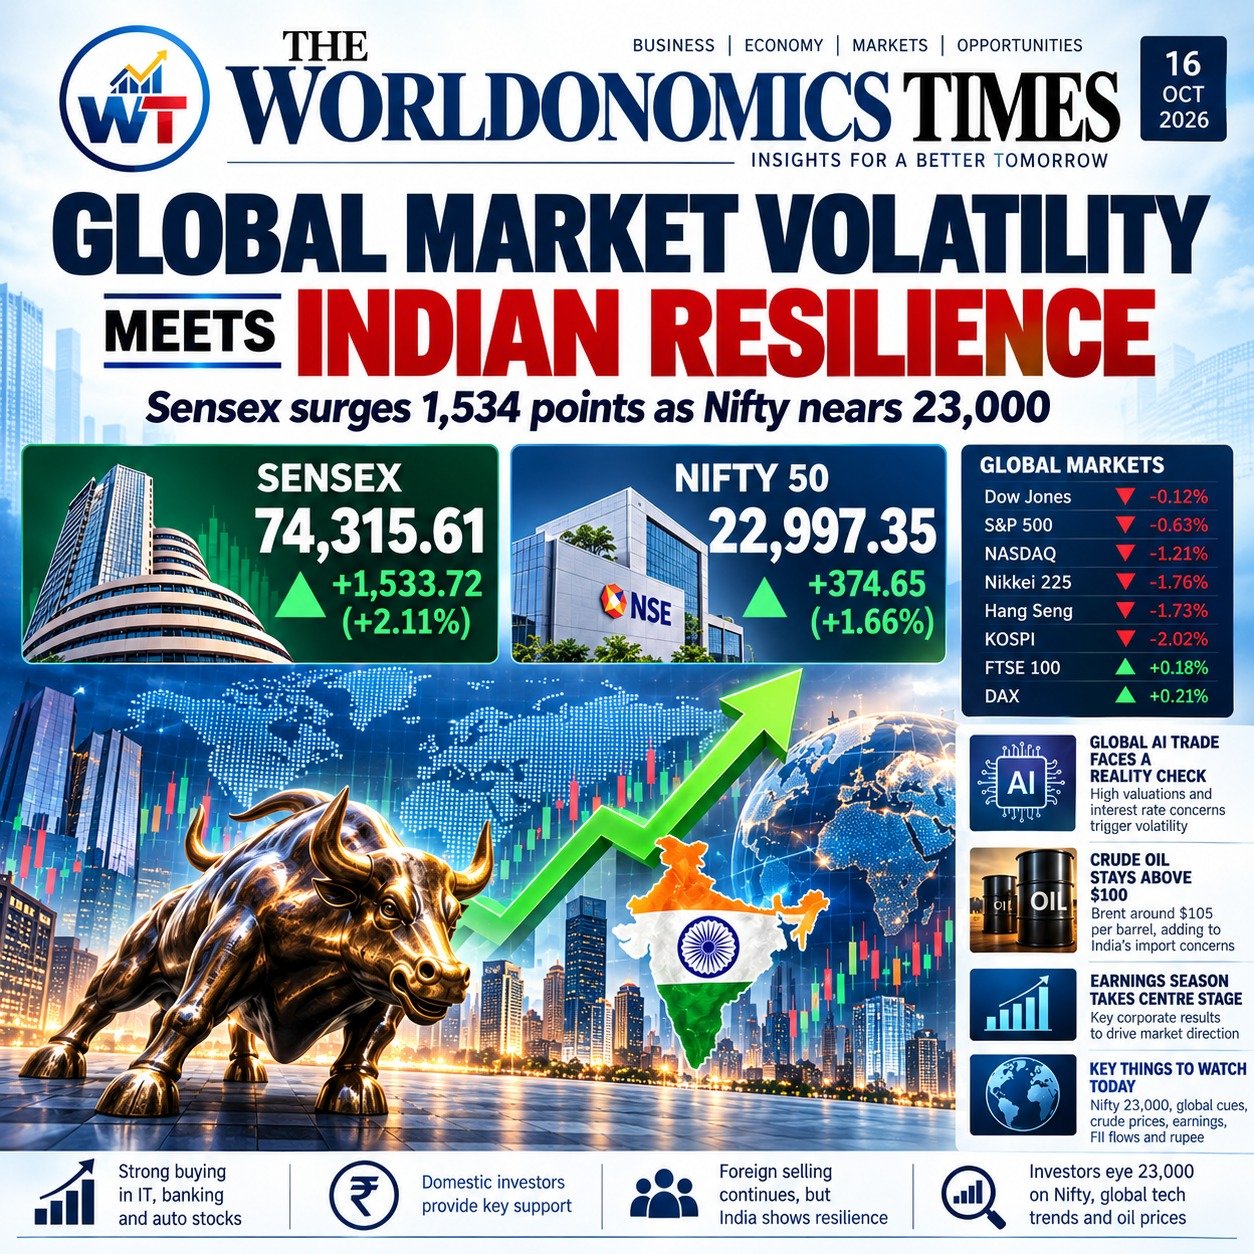
In the United States, equity futures indicated the possibility of a rebound after technology stocks suffered significant losses during the previous week. Nasdaq 100 futures were up about 1%, while S&P 500 futures gained around 0.5% in Monday trading. The Nasdaq 100 had fallen 5.5% during the previous week amid concerns about the enormous financing requirements associated with AI infrastructure.
The technology correction has become one of the most important themes influencing global markets. Investors are increasingly questioning whether revenues generated by artificial-intelligence businesses will justify the enormous capital expenditure required for data centres, semiconductor capacity and related infrastructure.
This has created pressure on highly valued technology and semiconductor companies, while also raising concerns about corporate credit spreads and financing costs.
Asia Sends Mixed Signals
Asian markets also remained volatile.
South Korea’s KOSPI rebounded 1.8% after suffering a major decline during the previous week. Japan’s Nikkei 225 slipped around 0.6%, with technology companies among the major sources of weakness. Meanwhile, China’s Shanghai Composite showed resilience, supported by economic data indicating stronger-than-expected GDP growth.
Groww’s global indices platform tracks major international benchmarks including the Dow Jones, S&P 500, Nikkei 225, Hang Seng, DAX, CAC 40, KOSPI and FTSE 100, providing investors with a consolidated view of global market movements.
The contrasting performance of Asian markets underlines the increasingly selective nature of global investing. Markets with strong technology exposure remain vulnerable to valuation adjustments, while economies benefiting from domestic demand or relatively supportive economic conditions are showing greater resilience.
Europe Faces Political and Economic Uncertainty
European equities were also under pressure. France’s CAC 40 declined around 1.3% in early trading, while Britain’s FTSE 100 and Germany’s DAX also moved lower. Political uncertainty in France added another layer of risk to an already cautious investment environment.
European investors are simultaneously monitoring inflation, interest-rate expectations, currency movements and corporate earnings. The direction of bond yields remains particularly important because higher yields can make equities relatively less attractive and increase financing costs for companies.
Oil Remains a Key Risk for India
Crude oil continues to be one of the most important variables for Indian investors.
Brent crude was trading around $108 per barrel, even after oil prices declined following the United States’ decision to waive certain sanctions and tariffs affecting Russia. Continuing tensions in the Middle East, including risks around the Strait of Hormuz, remain a major source of uncertainty.
For India, elevated crude prices can increase the import bill, place pressure on the rupee and potentially complicate inflation management. This makes oil particularly important for sectors such as aviation, transportation, chemicals and paints, while also influencing the broader macroeconomic outlook.
Earnings Season Takes Centre Stage
The coming days are expected to remain highly eventful as investors digest corporate earnings across major economies.
In India, investors are watching banking, technology, infrastructure and consumer companies closely. Globally, major US technology and consumer companies are also scheduled to report results, potentially providing fresh clues about corporate spending, artificial intelligence investment and the strength of consumer demand.
The upcoming Jio Platforms IPO is another major event for the Indian capital market. The issue is expected to attract significant attention from domestic and international investors and could become one of the year’s most closely watched market events.
The Worldonomics Outlook
The global market environment is increasingly being shaped by three competing forces: economic growth, corporate earnings and geopolitical risk.
For India, domestic economic fundamentals remain an important source of resilience, but international crude prices, foreign institutional flows, global technology valuations and currency movements can create short-term volatility.
The next few trading sessions could therefore remain sensitive to earnings announcements, crude oil movements and developments in global technology stocks.
For investors and businesses, the current environment reinforces the importance of monitoring both Indian and international indices rather than viewing markets in isolation. The growing integration of capital markets means that developments in Wall Street, Asia, Europe, commodities and currencies can quickly influence Indian asset prices.
The Worldonomics Times will continue to track the interaction between the Indian economy and global markets, bringing readers insights into the forces shaping investment, business and economic opportunities worldwide.
Market data is provided for informational purposes only and should not be construed as investment advice or a recommendation to buy or sell any security.