Global Markets Stabilise as Indian Equities Deliver Strong Weekly Gains
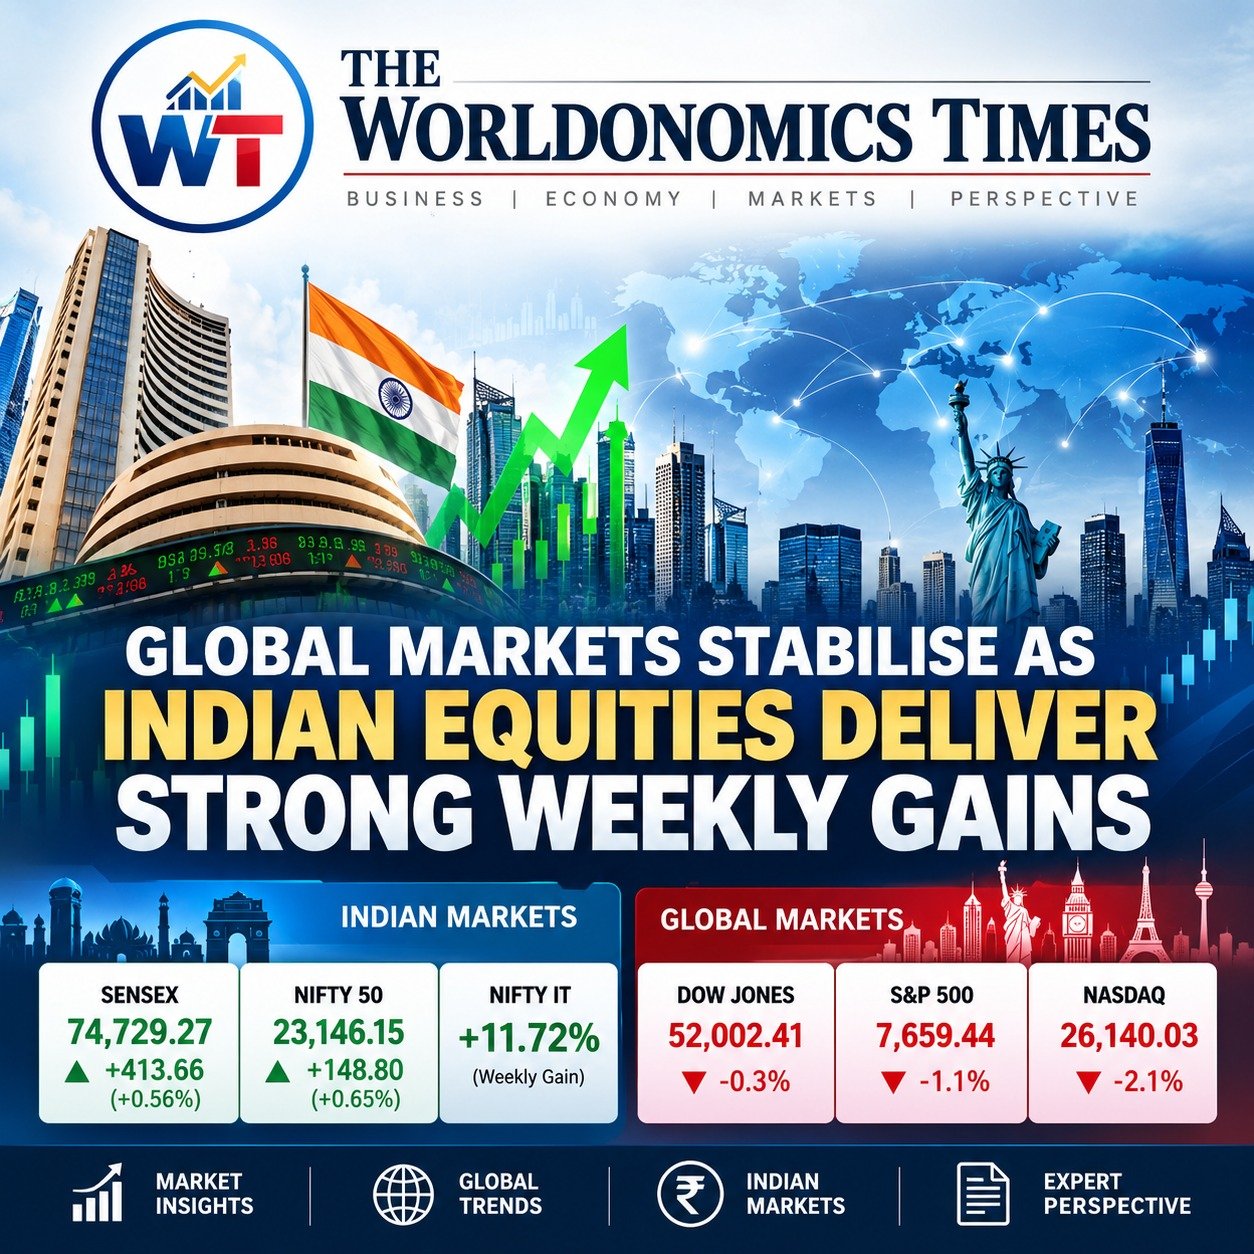
Indian Market Shows Resilience While Global Investors Navigate AI, Inflation and Interest-Rate RisksGlobal financial markets ended the week on a mixed but highly eventful note, with investors balancing optimism over corporate earnings and easing market stress against concerns surrounding inflation, interest rates, technology valuations and the debt financing behind the artificial intelligence boom. In India, benchmark equity indices demonstrated considerable resilience and recorded their strongest weekly performance in six months. The BSE Sensex gained 413.66 points, or 0.56%, on Friday to close at 74,729.27, while the Nifty 50 advanced 148.80 points, or 0.65%, to 23,146.15. On a weekly basis, the Sensex gained 3.11% and the Nifty rose 2.78%. The performance marked the second consecutive session of gains for both benchmarks.
Indian Equities: IT Leads the Recovery
One of the most striking developments in the Indian market was the exceptional performance of information technology stocks. The Nifty IT index surged 11.72% during the week, its strongest weekly gain in approximately 18 years. Technology stocks received support from quarterly earnings, improving investor sentiment and expectations surrounding global technology spending.Major technology names including Tech Mahindra, TCS and Infosys were among the prominent contributors to Friday’s market gains. Auto, media and metal stocks also supported the broader recovery.
The Indian rupee’s appreciation and softer crude-oil prices provided additional support. Investors also remained hopeful about progress towards an India-US trade agreement and possible policy developments relating to long-term capital gains and securities transaction taxation.
However, the broader market did not participate as strongly as the large-cap benchmarks. The Nifty Midcap 100 rose only 0.58% for the week, while the Nifty Smallcap 100 declined 0.12%, highlighting the continued preference for relatively established companies during a period of elevated uncertainty.
IGlobal Markets: Technology Stocks Under Pressure
The international picture remained considerably more volatile. US equities suffered a sharp technology-led decline on Friday.
The S&P 500 fell 1.1% to 7,659.44, while the Nasdaq Composite dropped 2.1% to 26,140.03. The Dow Jones Industrial Average declined a more modest 0.3% to 52,002.41. The Nasdaq and S&P 500 recorded their weakest sessions since June.
For the week, the Nasdaq declined 4.5%, the Russell 2000 fell 3%, and the S&P 500 lost 1.9%. The Dow, however, managed to post a 0.7% weekly gain. Despite the correction, all four major US indices remained positive for the year.
The sell-off was particularly severe in semiconductor and technology stocks. Concerns about the sustainability of exceptionally high AI-related valuations have intensified as investors examine the large amounts of debt being used to finance the expansion of AI infrastructure.
The Dow Jones remains one of the world’s most closely followed benchmarks. Groww describes it as a price-weighted index comprising 30 large US companies and an important indicator of the performance of major American businesses.
Asia Attempts a Recovery
Asian markets showed signs of stabilisation on Friday following the sharp sell-off in the previous session. South Korea’s KOSPI rebounded around 3%, while Japan’s Nikkei gained approximately 1.5%, recovering part of their earlier losses.
Nevertheless, investors remain cautious. Concerns over AI-related corporate debt, semiconductor competition and the direction of US monetary policy continue to influence global risk appetite.
China’s progress in next-generation memory technology has also raised questions about the competitive position of established global semiconductor manufacturers. This has added another layer of uncertainty to a technology sector already facing elevated valuation concerns.
European Markets Remain Watchful
European equities also showed signs of stabilisation after the technology-led global sell-off. Germany’s DAX, a key European benchmark tracking major German companies, is particularly important because of Germany’s exposure to manufacturing, automobiles, chemicals, technology and international trade. However, European investors continue to monitor inflation, bond yields, energy prices and the outlook for interest rates. These factors remain critical for corporate borrowing costs and equity valuations.The Worldonomics Times View
The coming week could be important for Indian markets as investors turn their attention to corporate earnings, particularly major banking companies. Market participants will also track developments in crude oil, the rupee, foreign portfolio flows, US interest-rate expectations and global technology stocks.
Technically, the Nifty is approaching the 23,300 zone, which market participants are watching as an important resistance level. A sustained move above this area could improve the possibility of a further recovery, while the 22,700–22,900 zone remains an important support area.
The larger message from the week’s trading is clear: Indian equities are showing relative strength, but global volatility has not disappeared. Investors therefore need to balance optimism with discipline. Strong earnings, domestic liquidity and improving sentiment can support Indian markets, but international developments—particularly US monetary policy, AI valuations, bond yields, crude oil and geopolitical risks—can quickly influence domestic sentiment.
For long-term investors, the current environment reinforces the importance of diversification, quality businesses, reasonable valuations and disciplined asset allocation rather than reacting to short-term market swings.
Market Snapshot:
Sensex: 74,729.27
Nifty 50: 23,146.15
Sensex Weekly Gain: 3.11%
Nifty Weekly Gain: 2.78%
Nifty IT Weekly Gain: 11.72%
S&P 500: 7,659.44
Nasdaq: 26,140.03
Dow Jones: 52,002.41